Tax
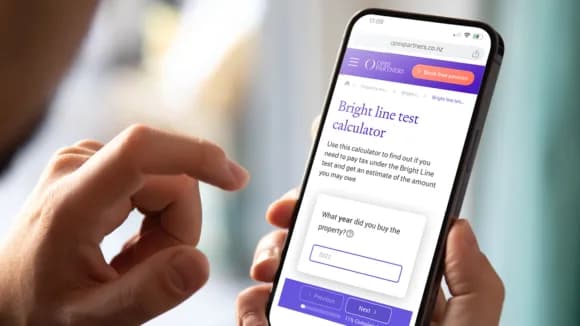
Bright line test calculator
Find out if you need to pay tax under the Bright Line test
Tax
12 min read

The bright-line test is a way to tax the profit made from buying and selling property quickly. It’s New Zealand’s lite version of a Capital Gains Tax.
The bright-line test is currently 2 years. This means, if you buy a residential property and then sell it within 2 years of owning it, you may have to pay tax.
This 2-year test applies to all properties no matter when you bought them.
Previously, the bright-line test was five or even ten years. It was very confusing. Some properties had a five-year test, and some had a ten-year test.
But the current National government changed the rules. So, all properties now have a 2-year test.
In this article, you’ll learn what the bright-line test is and who it applies to. You’ll also learn where Kiwis often get caught out.
Just because New Zealand doesn’t have an official Capital Gains Tax ... doesn’t mean all capital gains are tax-free.
We have an intention-based tax system for property. This means if you buy a property and intend to profit from capital gains, you’ll pay tax on any value increase.
You’re probably thinking: “But how do they prove I intended to profit from the capital gains?”
You’re right. Your initial intention when buying a property is hard to prove.
This is why we have a bright-line test. It was first introduced by John Key’s National government in 2015.
At that stage, if you sold a property within two years of buying, you had to pay tax on any capital gain.
Three years later, Labour extended the bright-line test to five years. Then, in 2021, they extended it again to 10 years.
National has now reduced the bright-line test back to 2 years.
This shorter bright-line test applies to all properties no matter when you bought them. It’s not just properties bought after July 1st (when National officially changed the rules).
Every residential property in New Zealand has a 2-year bright-line test.
So, if your previously had a five or 10-year bright-line, it is now two years.
Before the rules changed, it was so confusing:
| Old bright-line period | New bright-line period | |
|---|---|---|
| Property bought after March 27, 2021 | 10 years | 2 years |
| New Build bought after March 27, 2021 | 5 years | 2 years |
| Property bought March 29, 2018 – March 27, 2021 | 5 years | 2 years |
| Property bought before March 28, 2018 | No longer applied | 2 years |
Let's say you bought a property in June 2022. Under previous rules, you could get a hefty tax bill if you sold before June 2032.
But when the test changes, the bright-line expired in June 2024. Eight years earlier.
How much tax you pay (as a percentage) changes for each person. That’s because, under the bright-line test, you pay tax at your income tax rate.
New Zealand has a progressive tax system.
If you make more money, you pay a higher percentage of your income in taxes.
For instance, if you already pay the top tax rate because your income is above $180,000 ... you would then pay 39% in tax on any gains from property.
But if you earn $50,000 from your job, your tax rate is lower. So, you’ll pay less tax.
Use the calculator below to find out if you need to pay tax under the bright-line test and get an estimate of the amount you may owe.
The bright-line test calculates your net gain from a property transaction.
Let’s say you buy an investment property for $400k. Then you sell it for $500k a year later.
You made $100k, but you probably won’t pay tax on the entire gain. That’s because you may have incurred other costs like:
These costs can generally be deducted from your gain, as long as you haven't already claimed them elsewhere.
The leftover amount is added to your taxable income, and you pay tax based on your normal income tax rates.
For example, say an investor buys a property for $400k and spends $40k renovating it.
A year later, they sell the property for $550k and pay $25k in real estate agent fees.
They've sold the property for $150,000 more than they paid for it. But they've also spent $65,000 renovating and selling it.
That leaves them with a taxable gain of $85,000 ($150,000 minus $65,000).
If they also earn a $70,000 salary, the $85,000 gain takes their total taxable income to $155,000.
New Zealand has progressive tax rates, so they don't simply pay one tax rate on the whole $85,000 gain.
The first $8,100 of the gain is taxed at 30%, and the remaining $76,900 is taxed at 33%.
That means they'd pay about $27,807 in additional income tax on the $85,000 gain.
That leaves them with about $57,193 after tax from that gain.
At a glance:
| Item | Amount |
| Sale price | $550,000 |
| Purchase price | $400,000 |
| Gross gain | $150,000 |
| Renovation costs | $40,000 |
| Real estate fees | $25,000 |
| Total deductible costs | $65,000 |
| Taxable gain | $85,000 |
| Salary | $70,000 |
| Total taxable income | $155,000 |
| Tax on gain | 30% and 33% |
The bright-line test doesn’t apply to every property. Here are the properties the test does not apply to:
The bright-line test intends to target short-term property speculators. That’s why it generally doesn’t apply to your main home. That means you can buy and sell your main home without paying taxes.
But you can only have one main home. That means if you buy a holiday home and sell it within the bright-line period, you’ll pay income tax on any net gain.
On top of this, the property has to have been your main home for at least 50% of the time that you've owned it.
So if you buy a property – live in it for 6 months, rent it out for a year, then sell – you'll need to pay tax on your gains.
The bright-line test also doesn’t cover inherited property.
If a parent dies and leaves the property to you and your siblings and you sell you don’t have to pay tax on any of it.
Again, there are some intricacies. We’ll discuss below.
And, of course, if you buy a property and sell it over 2 years later you will also not pay tax on the gains. This is true, even if it was an investment property.
If you sell a property within the bright line and the property isn’t:
Then you need to pay income tax on any gain you’ve made, but there are other fishhooks.
Here are a few examples where people accidentally had to pay under the bright-line test:
Say a couple earn $100,000 each a year and like buying and renovating properties.
They buy a cheap house that needs some love. They live there during the renovations and sell it three months later for a $50,000 gain.
They then buy another property, spend six months renovating it, and sell it for an $80,000 gain.
Both properties qualify for the main home exclusion, so the gains aren't taxable under the bright-line test.
But there are limits to how often you can use this exclusion.
You can't use the bright-line main home exclusion if you've already used it twice in the previous two years.
So, say the couple buy a third property, renovate it and sell it within three months for a $40,000 gain.
This time, they can't use the main home exclusion because they've already used it twice in the previous two years.
The $40,000 gain is taxable under the bright-line test.
If the gain is attributed equally between them, that's $20,000 of extra taxable income each. Since they already earn $100,000 each, that extra income falls within the 33% tax bracket.
Together, they'd pay $13,200 in tax on the $40,000 gain.
There are other tax rules to watch too.
If you regularly buy and sell your main home, IRD may decide you've established a regular pattern of buying and selling property. And if you bought a property with the intention of selling it, the gain may be taxable under the intention rule.
So, simply living in a property while you renovate it doesn't automatically mean your gain will be tax-free.
At a glance:
| Item | Amount |
| Taxable gain (third property) | $40,000 |
| Tax rate | 33% |
| Tax owed to IRD | $13,200 |
If you turn you live in a property then turn it into a rental, you may need to pay tax.
It’s called the “change-of-use” rule.
A property can only use the main home exemption if it has been your main home for at least 50% of the time that you've owned it.
So if you buy a property – live in it for 6 months, rent it out for a year, then sell – you'll need to pay tax on your gains.
Property investors can get caught when moving properties between entities.
For example, say an investor buys an investment property for $500k.
A year later, the property is worth $600k and they want to refinance and move the property from their personal name into a Look-Through Company.
On paper, the property has increased $100,000 in value.
Usually, selling a property within the 2-year bright-line period could mean that $100,000 gain is taxable.
But there is an exception.
Since 1 July 2024, some transfers between associated people and entities can qualify for rollover relief.
So, if the investor owns the LTC and the transfer meets the rollover relief rules, they may pay $0 in bright-line tax when the property is transferred.
Instead, the LTC generally takes over the investor's original purchase price and purchase date.
That means, for bright-line purposes, the LTC is treated as though it bought the property for $500k a year earlier.
If the transfer doesn't qualify for rollover relief, the tax outcome could be very different. The $100,000 gain may be taxable if the transfer falls within the bright-line rules.
That's why it's important to get tax advice before moving a property between entities.
At a glance:
| Item | Amount |
| Original purchase price | $500,000 |
| Value when transferred to LTC | $600,000 |
| Increase in value | $100,000 |
Let’s say you want to transfer a property from your own name to your family trust.
You’re outside the bright-line test, so you didn’t get caught like Rob did in the previous example.
But that resets the bright-line test.
Let’s say you bought an investment property in 2016 and sold it to your family trust in 2024.
You’re outside the bright-line test, so you don’t pay tax. But because the property has now changed hands, the bright-line test resets.
Yes, even though you have – in effect – just sold it to yourself. This means you now need to wait another 2 years before you are outside the bright-line.
Developers, property traders and builders all get tougher rules under the bright-line test. They are “tainted”.
So if you are involved with:
You may still need to pay tax on your capital gains (even if you are outside the normal bright-line test).
In this case, do yourself a favour and talk to a property accountant. Ask them whether you need to pay tax on your property sales. You don’t want to receive a call from the IRD asking you to pay a 5-figure tax bill.
This article will give you a sense of how complicated property tax can be in New Zealand.
There are rules, and then there are exemptions (and exceptions) to those rules. And then there is how those rules are interpreted. This is why you must consult a property tax accountant and lawyer when buying property.
If you are looking for a property accountant, you might like to talk to our team at Opes Accounting.
Resident Economist, with a GradDipEcon and over five years at Opes Partners, is a trusted contributor to NZ Property Investor, Informed Investor, Stuff, Business Desk, and OneRoof.
Ed, our Resident Economist, is equipped with a GradDipEcon, a GradCertStratMgmt, BMus, and over five years of experience as Opes Partners' economist. His expertise in economics has led him to contribute articles to reputable publications like NZ Property Investor, Informed Investor, OneRoof, Stuff, and Business Desk. You might have also seen him share his insights on television programs such as The Project and Breakfast.
This article is for your general information. It’s not financial advice. See here for details about our Financial Advice Provider Disclosure. So Opes isn’t telling you what to do with your own money.
We’ve made every effort to make sure the information is accurate. But we occasionally get the odd fact wrong. Make sure you do your own research or talk to a financial adviser before making any investment decisions.
You might like to use us or another financial adviser