
Property Investment
The election is over. How likely are these 4 property tax changes?
4 big property tax changes were on the table this election. How many will actually happen? 👇
Property Investment
3 min read

Author: Andrew Nicol
Founder, 20+ Years' Experience Investing In Property, Author & Host
Most people have no idea whether they’re on track to retire.
They’ll know roughly how much is in their KiwiSaver. They assume they’ll receive NZ Super.
They might even own an investment property.
But they’ve never put all those numbers together and asked: “Will this actually be enough?”
It's a big enough problem – I wrote a whole book about it.
So I built you this new retirement calculator. That way, you can find out if you're on track, today.
Let's take an average example I see every day.
A couple who are both 45. They'd like to retire at 65.
One partner earns $100k a year, the other earns $75k. They’ve both got pretty normal KiwiSaver balances for their incomes – $50k and $30k.
What sort of retirement do they want?
Enough to enjoy a ‘Choices’ lifestyle (currently about $93,000 a year).
That’s based on Massey University’s 2025 Retirement Expenditure Guidelines.
So… are they on track? Here’s what their future looks like 👇
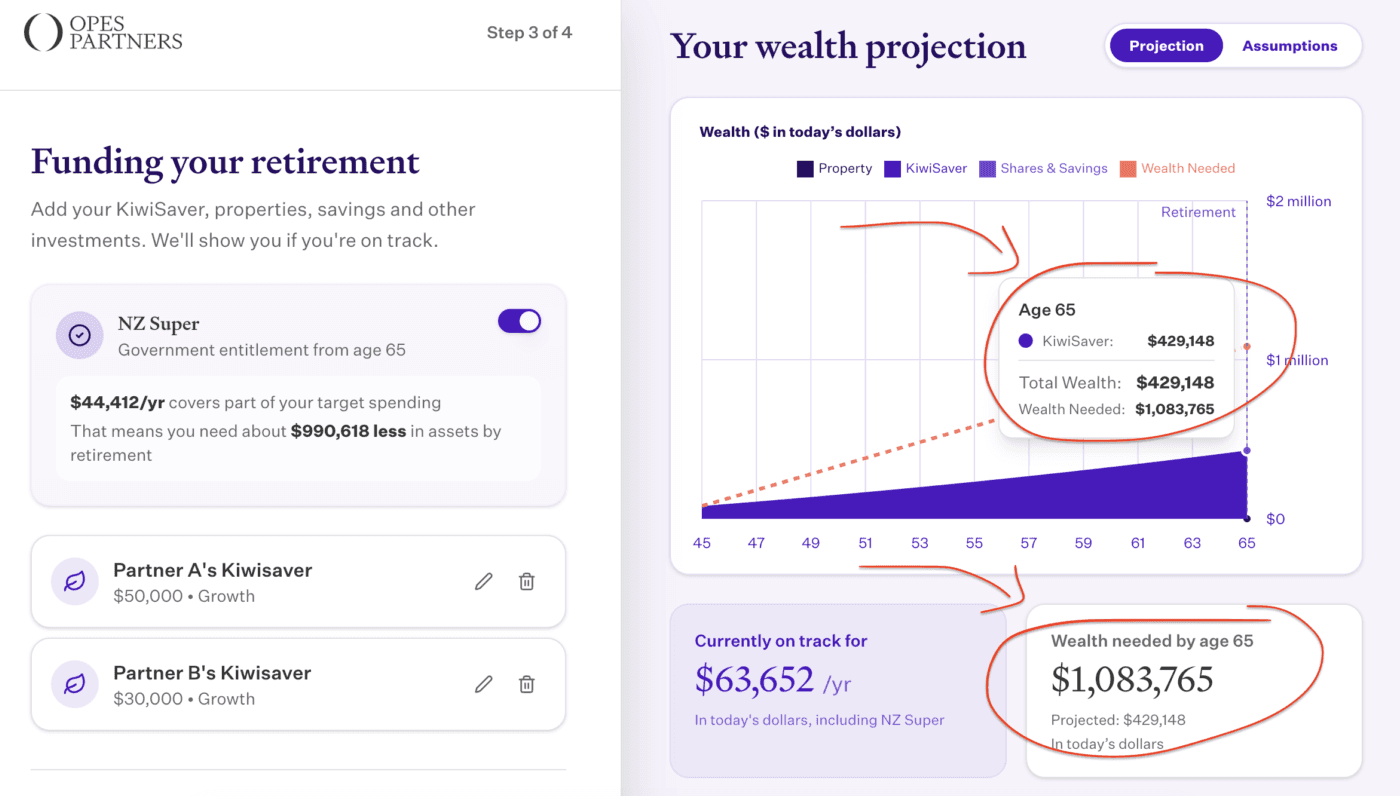
Their KiwiSaver is doing a lot. It’s projected to add up to almost $430k by the time they retire.
But to spend that $93k a year, they’d need just over $1 million ‘in the bank’ when they retire.
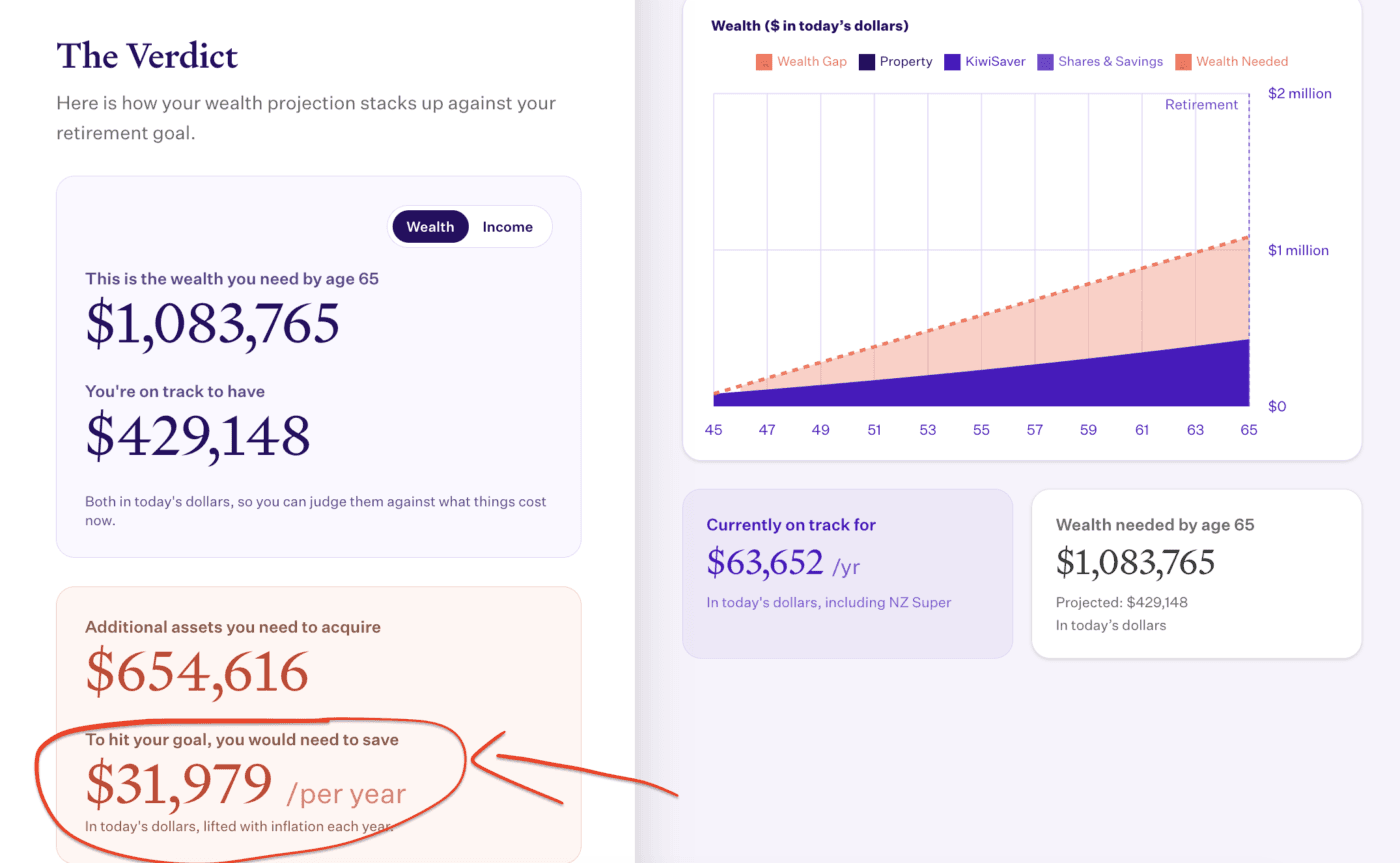
They’re about $1 million short. So – like most Kiwis – they have a Wealth Gap.
A Wealth Gap is the difference between the retirement you want... and the retirement you’re currently on track to afford.
It basically asks: “if you keep doing what you’re doing money-wise, will you have enough money to retire the way you want?”
If the answer is ‘no’, you have a Wealth Gap.
And with this couple, the calculator estimates they'll be $564 short per week in retirement. (That’s compared to what they want to spend).
To close that gap through savings alone, they'd need to put away another $32,000 every year.
That’s a problem worth solving.
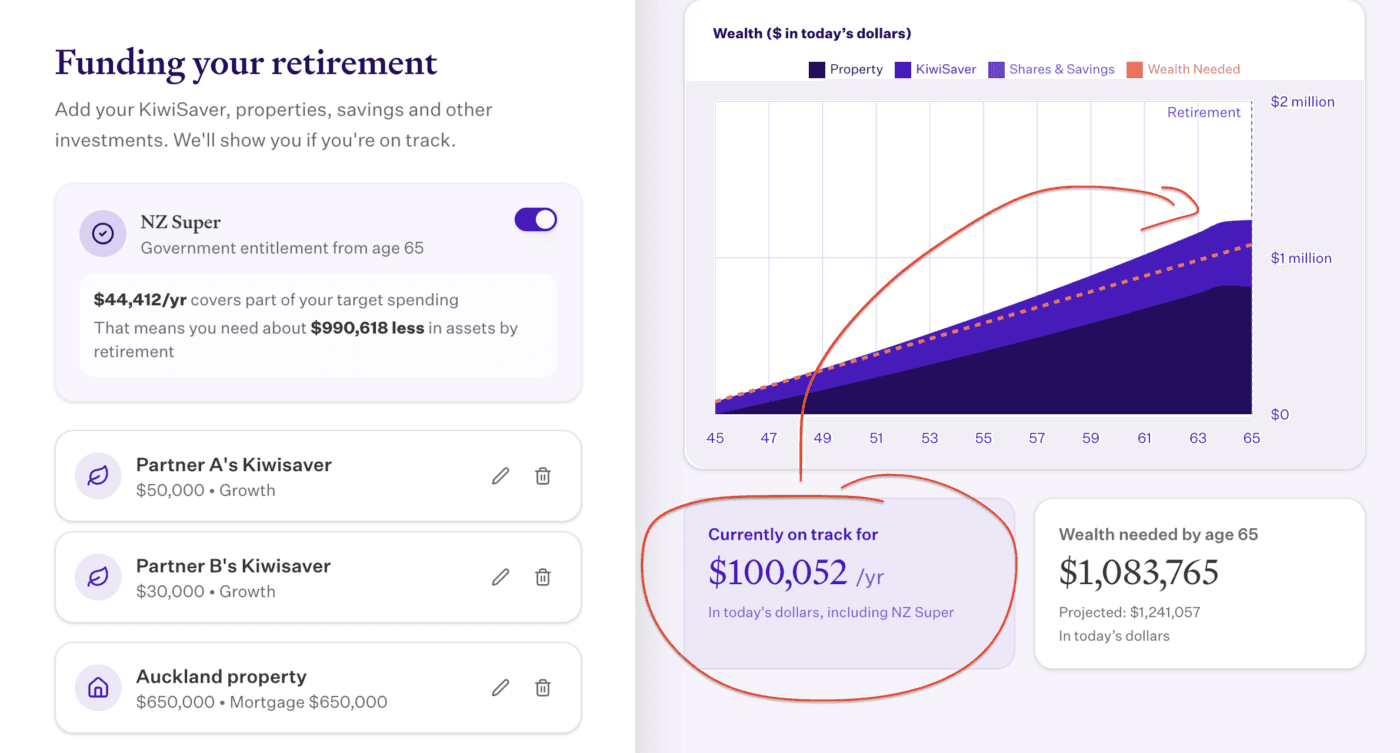
Now let's meet another couple. They’re in the same position; except they own an investment property.
Let’s say they bought a $650,000 investment property in Auckland.
They borrowed the full purchase price. And for this example, let's say they use an interest-only loan.
If that property goes up in value by 6% a year, then by the time they’re 65, they’re projected to have closed their Wealth Gap.
It doesn’t mean they’re wealthy today. But if their investments go up in value as projected, then they’ll have closed their Wealth Gap.
Is 6% growth the right number to use?
Since 1992, if you held an Auckland property for 10+ years, Auckland house prices grew at least 6% a year, 86% of the time.
That assumes your property followed the market perfectly. (Source: REINZ House Price Index, 1992–April 2026.)
The point of this isn’t to say that everyone should invest in property.
My point is something much bigger.
Retirement isn't about hoping everything works out. It's about building a plan.
Sometimes that plan is KiwiSaver. Or managed funds. Or property.
Often, it's a combination of all three.
But until you run the numbers, you’ve got no idea.
If you use this calculator, in a few minutes you'll see whether you're on track ... or if you've still got a gap to close.
The good news is:
Once you know if you've got a Wealth Gap, the next step is to close it.
That's a conversation you have with a financial adviser.
You might like to use my team at Opes Partners, or someone else. If
it's us, use this link to book a free portfolio planning session.
Founder, 20+ Years' Experience Investing In Property, Author & Host
Andrew Nicol, Managing Director at Opes Partners, is a seasoned financial adviser and property investment expert with 20+ years of experience. With 40 investment properties, he hosts the Property Academy Podcast, co-authored 'Wealth Plan' with Ed Mcknight, and has helped 1,894 Kiwis achieve financial security through property investment.
This article is for your general information. It’s not financial advice. See here for details about our Financial Advice Provider Disclosure. So Opes isn’t telling you what to do with your own money.
We’ve made every effort to make sure the information is accurate. But we occasionally get the odd fact wrong. Make sure you do your own research or talk to a financial adviser before making any investment decisions.
You might like to use us or another financial adviser


