Financial Adviser
Is Opes the right fit for me? (The answer may be ‘no’)
Is Opes Partners right for you? Find out who Opes suits, who it doesn't, and whether its New Build property investment strategy matches your goals.
Opes
9 min read


Author: Stevie Waring
Financial Adviser with 7 years of experience. Property investor in Wellington and Christchurch
Reviewed by: Ed McKnight
Resident Economist, with a GradDipEcon and over five years at Opes Partners, is a trusted contributor to NZ Property Investor, Informed Investor, Stuff, Business Desk, and OneRoof.
As at August 2026, Opes generally recommends investment properties in:
We sometimes consider dual-key properties in Auckland, Queenstown and Wellington. These are usually for investors who are focused on rental yield.
But we don’t recommend every property in these markets. The right property type depends on the area, and the right area depends on what you’re trying to achieve.
In this article, you’ll learn in which areas Opes recommends buying investment property and why.
Opes currently focuses on Auckland, Christchurch, Selwyn and Waimakariri. But the right location depends on your strategy, budget and whether you’re chasing capital growth, rental yield or a balance of both.
Opes’ recommendations aren’t just about picking a random city and buying a property there.
We look at things like property prices, rental yields, population growth and whether a market looks over or undervalued. We then look at which types of properties make the numbers work in that particular market.
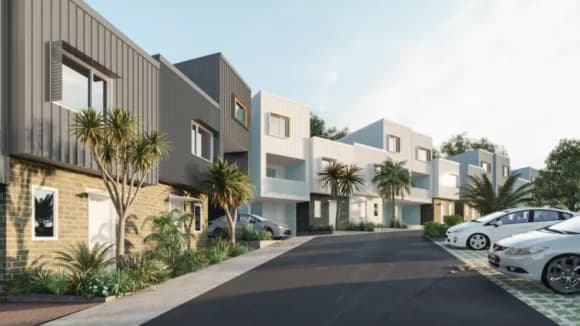
For example, we generally recommend:
A 2-bedroom townhouse might not be the right fit for Rolleston or Pokeno, where standalone houses are more common.
Likewise, a standalone house may not be the right fit for central Auckland. House prices can be too high to make the numbers work.
Here are the broad price and rental yield targets we use. Keep in mind these are target ranges, not guarantees.
Target price: $600,000-$1.2 million
Average house price: $940,000 (Jul 2026 – REINZ)
Undervalued by: 9.72% (July 2026)
Auckland is New Zealand’s biggest property market.
It’s more expensive than many other parts of the country, but its large and growing population gives us the confidence to recommend it for investors looking for long-term capital growth.
| Why Auckland can suit investors | What to watch out for |
| 💰 Appears undervalued | 💵 Higher purchase prices |
| 📊 Strong long-term growth | 📉 Lower rental yields |
| 👨👩👧👦 Strong population growth | 🏘️ More townhouses |
Auckland’s population is forecast to keep growing quickly.
Stats NZ projects the region will account for 44% of New Zealand’s total population growth between 2023 and 2053. It also says Auckland will reach 2 million people around 2033.
All these people need somewhere to live.
Now, as at July 2026, our analysis suggests Auckland property prices are around 9.72% undervalued.
Why is that important? Well, it means prices are below the level we would expect them to be.
Auckland also has a strong long-term track record.
Since 1992, Auckland property prices have increased to around 8.1 times their original level, compared with 6.8 times for the rest of NZ.
Loading...
The biggest drawback is price. Auckland properties cost more than other areas, so you’ll generally need a larger deposit and take out a larger mortgage.
Rental yields also tend to be lower, so you’re often paying more for the property without getting the same increase in rent.
And because land is expensive … townhouses are more common.
That’s not necessarily a bad thing, but investors who specifically want a standalone house may find it harder to make the numbers work.
Loading...
Auckland is a huge property market. Not every suburb is the same.
The five Auckland suburbs currently on our radar:
All five are fairly close to the CBD. That might seem a bit surprising because usually the closer you get to the city, the more expensive property is.
But Auckland house prices have fallen.
So, some of these central suburbs are now more affordable than they were a few years ago. And because rents have held up, the yields can meet our benchmarks too.
Of course, that doesn’t mean every property in these suburbs is a good investment.
| Suburb | Median house value | Capital growth |
| Mount Albert | $1,214,300 | 6.2% |
| Mount Roskill | $1,063,200 | 5.8% |
| Māngere Bridge | $1,0252,750 | 5.9% |
| Onehunga | $1,013,550 | 6.0% |
| Birkdale | $947,700 | 6.4% |
Target price: $550,000-$900,000
Average house price: $802,872 (QV, July 2026)
Undervalued by: 1.93% (July 2026)
Christchurch is another market we generally recommend to property investors.
It’s more affordable than Auckland and tends to offer higher rental yields. It also has a growing population.
Christchurch property is relatively affordable. The average house price is well below Auckland’s.
That makes Christchurch an option for investors who don’t have the borrowing capacity needed for Auckland.
Christchurch property also looks undervalued, but not by much. As at July 2026, our analysis suggests the market is around 1.93% undervalued compared with where we would expect prices to be.
Christchurch also tends to offer a higher rental yield than Auckland.
Properties are cheaper, while rents remain relatively strong. That can make it easier to get the cashflow side of an investment working.
| Why Christchurch can suit investors | What to watch out for |
| 💰 Appears undervalued | 📊 Potentially slower capital growth than Auckland |
| 🏠 More affordable properties | 🛡️ Higher insurance costs |
| 💵 Higher rental yields | 📈 Market is already in recovery |
| 👨👩👧👦 Growing population |
The main trade-off is that Christchurch may not deliver the same level of capital growth as Auckland.
Also, insurance can cost more in Christchurch than in Auckland.
Quashed’s 2026 data puts the average Christchurch premium at $2,903 a year, compared with $2,063 in Auckland – a difference of $840.
In 2019, Christchurch property prices appeared to be heavily undervalued. House prices in the rest of the country had increased, and Christchurch house prices were relatively low. This gave us confidence the market may be in for catch-up growth.
Since then property values in the Garden City have appreciated faster than the rest of New Zealand (on average) so that catch-up growth has materialised.
Surprisingly, that is a downside of investing in Christchurch now, because investors have already gained some of that catch-up growth.
Loading...
Christchurch is a large market, so we wouldn’t recommend buying in any old suburb.
The five suburbs currently on our radar:
These suburbs tend to be on the more affordable side. So, you can potentially get access to the strong rental market … without paying through the nose for it.
| Suburb | Median house value | Capital growth |
| Spreydon | $637,950 | 5.9% |
| Addington | $567,150 | 6.1% |
| St Albans | $895,400 | 6.0% |
| Edgeware | $561,950 | 5.8% |
| Riccarton | $749,050 | 5.5% |
Target price: $670,000-$890,000
Average house price: Selwyn: $860,471. Waimakariri: $744,589 (QV, July 2026)
Undervalued by: Selwyn: 0.43% overvalued. Waimakariri: 2.07% (July 2026)
If you want to invest in Canterbury, but would prefer a standalone house, it’s worth looking at Rolleston, Kaiapoi and Rangiora.
These are growing towns in the Selwyn and Waimakariri districts, just outside Christchurch.
Standalone houses are still relatively affordable in these districts.
That gives investors the chance to buy into growing markets without paying Christchurch’s higher prices.
Selwyn District (where Rolleston is the largest town) has the fastest-growing population in the country.
Two-and-a-half decades ago Rolleston was a tiny town with less than 2,000 people, but it’s gone from a paddock to a town in just over 20 years.
Waimakariri's population is forecast to grow by around 25% by 2053.
More people means more looking for places to live. That can support demand for housing and rentals over the long term.
In both these areas standalone houses are the main property option.
Land is generally more affordable than in Christchurch. That makes it easier to buy a standalone house with a section while keeping the purchase price within the target range.
| Why Selwyn and Waimakariri can suit investors | What to watch out for |
| 💰 Appears undervalued | 👨👩👧 Smaller pool of tenants |
| 🏡 More affordable standalone houses | 🚘 Further from Christchurch CBD |
| 📈 Strong population growth | 🏘️ Fewer property types to choose from |
The biggest trade-off is tenant demand. These markets are smaller and further away than Christchurch, so there are fewer potential tenants.
And because these areas are dominated by standalone houses, there are fewer property types to choose from.
So, if you specifically want a townhouse … you’ll have to head back into Christchurch for more options.
For investors looking at this part of Canterbury, we would focus on:
| Suburb | Average house value | Capital growth |
| Rolleston | $818,900 | |
| Kaiapoi | $692,950 | 5.3% |
| Rangiora | $728,900 | 5.4% |
These towns appeal to investors who want an affordable standalone house, while still getting exposure to strong population growth.
But don’t assume every house in a fast-growing town will make a good investment.
Target price: $725,000-$999,000
Locations: Auckland, Queenstown and Wellington
Target rental yield: 6%+
Target capital growth: 3.5%-4.5%
If you’re looking for a higher-yielding investment, another option we may recommend is a dual-key townhouse or apartment.
A dual-key property typically has two separate living spaces within one legal title.
You can rent the two spaces to separate tenants, which can give you more rental income from one property.
The trade-off is that dual-key properties are generally more focused on rental yield so they don’t tend to rise in value as fast as some other types of properties.
| Why a dual-key can suit investors | What to watch out for |
| 💵 Higher rental yield | 📊 Potentially slower capital growth |
| 📍 Often in central locations | 🔧 Higher maintenance costs |
| 👨👩👧👦 Two rental incomes | 🚗 Some don’t have a car park |
The higher rental yield is the main attraction.
At Opes Partners we target a gross rental yield of 6% or higher for dual-income properties. That's higher than you’d typically get from a standard investment property.
Having two tenants can also spread your rental income across two tenancies.
If one side becomes vacant you will still have rent coming in from the other.
Dual-key properties are also often found in areas where rental demand is strong and higher-density housing makes sense.
We consider them in Auckland, Queenstown and Wellington.
The main trade-off is capital growth.
Because this is a yield property, dual-keys tend to grow more slowly than other types of investment.
You also need to allow for higher maintenance and operating costs because you’re effectively managing two living spaces.
And while two tenants can mean more rental income, it can also mean more complexity.
One side could be vacant while the other is occupied.
The locations we would consider for dual-key investments are:
These markets can work for dual-key properties because they have strong rental demand. And they’re also in areas where higher-density housing makes sense.
But again, we wouldn’t recommend a dual-key property simply because it’s in one of these cities.
There isn’t one market that will suit every investor.
If you’re focused on long-term capital growth, a large and growing market like Auckland could make sense.
If you want a balance between price, rental yield and growth, Christchurch could be worth a closer look.
If you want a more affordable standalone house in a fast-growing area, Rolleston, Kaiapoi or Rangiora might fit the bill.
And if your priority is rental income, a dual-key property in Auckland, Queenstown or Wellington could be a better fit.
But the area is only one part of the decision.
You still need to find a property that works at today’s price and rent, in a location with enough tenant demand, and with a reasonable chance of long-term growth.
You might be thinking, “What about Palmerston North?” Or Gore, Invercargill, Hamilton, Tauranga or somewhere else?
We don’t ignore those markets.
We're the data nerds, after all. We analyse property markets across New Zealand.
If a city isn’t on our recommended list, it’s not because we’ve forgotten about it.
It’s because, based on the data we’re looking at, we don’t think it’s one of the stronger markets for investors right now.
But that can change. And as the data moves, we update our recommendations.
If you’re not sure which market or strategy makes sense for you, you can book a free portfolio planning session with one of our financial advisers.
Your next step is to book a portfolio planning session. This is where a financial adviser will create you a financial plan. They will then find properties that fit your plan.
Book your free sessionFinancial Adviser with 7 years of experience. Property investor in Wellington and Christchurch
Stevie Waring is a Financial Adviser with over 7 years of experience in property investment and a successful investor herself. Stevie has successfully guided over 200 Kiwis in their property investments, helping them move closer to achieving their financial goals.
This article is for your general information. It’s not financial advice. See here for details about our Financial Advice Provider Disclosure. So Opes isn’t telling you what to do with your own money.
We’ve made every effort to make sure the information is accurate. But we occasionally get the odd fact wrong. Make sure you do your own research or talk to a financial adviser before making any investment decisions.
You might like to use us or another financial adviser